Understanding your options when selling an investment property.
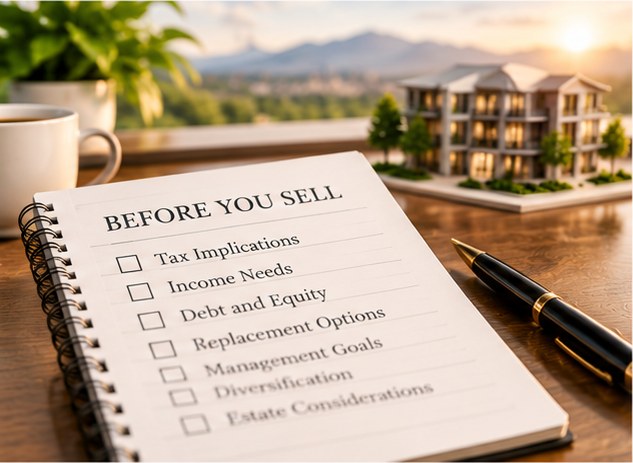
When selling an investment real estate property, a number of questions will likely surface.
What are the tax implications? What will I do with the sale proceeds? Do I need to replace the rental income? Do I want to stay in the landlord business?
Answering the first question is a good place to start and will help determine your best next steps. If your sale will trigger significant, taxable real estate gains, consider exploring the 1031 exchange strategy to defer taxes and keep more capital working in your portfolio.
1031 Exchanges
Managing Appreciated Real Estate with Greater Flexibility
Understanding the 1031 Exchange Learn how a 1031 exchange works, including the process, key requirements, important deadlines and the role of the Qualified Intermediary.
What is a 1031 exchange?
A 1031 exchange is a strategy that allows you to defer capital gains taxes on the sale of a qualifying investment property by reinvesting the sale proceeds into other investment real estate. Tax deferral may allow you to keep more capital invested in real estate rather than using a portion of the sale proceeds to pay current taxes.
The Basic Client Example
Without planning
Client sells
Taxes are paid
Less capital is available to reinvest
The Planning Opportunity — Keep More Capital Working
With a successful 1031
Client sells
Proceeds go through a Qualified Intermediary (QI)
Like-kind property is acquired
Tax may be deferred
Of course, like any tax strategy, there are strict stipulations as to how a 1031 exchange must be executed, including a strict 180-day timeline.
1031 Exchange Process
To defer capital gains taxes from your sale, you generally must:
Buy an investment property of equal or greater value than the investment property sold
Reinvest all net proceeds from the sale
Replace any debt associated with the original property or add equivalent cash
Acquire only like-kind property
Like-Kind Exchange Requirement
In order to qualify for a 1031 exchange, the property sold and the property purchased must be considered like-kind. Like-kind does not mean identical. Generally it means investment real estate for investment real estate.
Examples
Rental house → multifamily
Land → industrial
Retail → apartments
One property → multiple properties
Direct property → qualifying Delaware Statutory Trust (DST) interest
By making a like-kind exchange, you are not required to recognize a gain under Internal Revenue Code Section 1031, hence the name 1031 exchange.
Role of the Qualified Intermediary (QI)
Another important stipulation is that you cannot take control of the sale proceeds. Instead, you must hire a Qualified Intermediary (QI) to serve as a principal to facilitate the 1031 exchange transaction. The QI will have specialized 1031 exchange experience and likely be in the legal or accounting profession.
The QI will:
Temporarily hold the 1031 exchange funds (as the seller, you may not take control of sale proceeds)
Prepare the legal documentation
Coordinate the exchange documentation
Facilitate the sale and replacement process
Time-Sensitivity of the Exchange
A 1031 exchange runs on a tight calendar that leaves no margin for error. The clock starts as soon as your property sale closes, at which point you have 45 days to identify up to three potential replacement properties. You must close on your new investment property by day 180. If you miss this deadline, you lose the tax deferral.
Day 0
Property sold; proceeds go to Qualified Intermediary
Day 45
Potential replacement properties must be identified
Day 180
Replacement property must be acquired
Not adhering to the 1031 exchange schedule will cost you the tax deferral opportunity.
DSTs and the 1031 Exchange Explore how Delaware Statutory Trusts (DSTs) can be used as replacement property in a 1031 exchange and understand their potential benefits and considerations.
Delaware Statutory Trusts (DSTs) as a Replacement Property Strategy
A Delaware Statutory Trust (DST) is a trust structure that can own real estate. A DST may own one or more real estate investment properties that are often institutional-quality and professionally managed.
Investors own beneficial interests in the trust. This direct ownership classification qualifies a beneficial interest in a DST as a replacement property for Section 1031 exchanges.
The Potential Benefits of Using a DST as Part of Your 1031 Exchange
Besides being a strategic alternative to buying a new property, a DST may also help real estate investors address personal or estate concerns.
For instance, if you are ready to give up being a landlord and all the work that entails, a DST investment may make sense. Or, if your heirs do not want to own and manage your rental property, consider exchanging into a DST. Taking a fractional share in a DST helps address these common concerns, while allowing you to still participate in the investment real estate market.
Potential benefits of a DST as a replacement property may include:
Tax deferral potential
Reduced landlord responsibilities
Diversification across markets or property types
Estate planning flexibility
Passive real estate income
Professional management
A way to match exchange proceeds
Replace recourse debt with non-recourse debt
DSTs can solve 1031 timing issues, as well as property management fatigue, estate planning concerns, portfolio diversification concerns, and replacement debt needs.
Potential Roles of a DST in a 1031 Exchange
As with any real estate investment, due diligence is important when considering DSTs. Once you’ve identified a DST, consider how you will use it for your 1031 exchange. It can be used in a number of ways.
A DST can be used as:
A full replacement-property strategy
A backup identification option
A diversification tool
A partial replacement-property strategy
A debt-replacement tool
A passive ownership transition
Comparing Two Approaches to the 1031 Exchange Strategy See how different approaches to completing a 1031 exchange compare, including direct property ownership and DST investments.
A 1031 exchange can be completed through direct ownership of a replacement property or through a Delaware Statutory Trust (DST). Each approach offers different considerations around control, responsibility, timing, diversification, and ongoing management.
Direct Replacement Property
More control
More responsibility
May be harder to identify and close
May concentrate risk
DST Replacement Property
Passive ownership
Can help with timing
Potential to provide diversification
May support income replacement
Requires careful due diligence
Continue Learning Explore additional resources and insights to help you better understand real estate investing and 1031 exchange strategies.
Real Estate Insights
Interested in learning more?
We share further insights on real estate development below.
Delaware Statutory Trust (DST) interests are securities and are offered only by means of a Private Placement Memorandum (PPM) to accredited investors, as defined under Regulation D of the Securities Act of 1933. There is no guarantee that any investment objective, targeted distribution rate, or return of principal will be achieved. DST investments involve substantial risk, including illiquidity, lack of a secondary market, potential loss of the entire principal invested, and reliance on the performance of the underlying real estate. Past performance is not indicative of future results. DST offerings are not FDIC insured, are not bank guaranteed, and may lose value. This material is for educational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any security, nor does it constitute tax, legal, or investment advice — consult your own qualified professional before making any investment decision. Investment advisory services related to 1031/DST planning are offered through Dyche Wealth Management, Inc., an SEC Registered Investment Advisor, operating as Dyche, Riley & Selman Wealth Management. DST securities are offered by the sponsor through its designated broker-dealer.